Seller Guide · by Aidan Sowa · October 6, 2026
How to Prepare NoDa Edge Association and Parking Records Before Selling
Separate ownership, shared costs and parking rights before comparing sale terms.
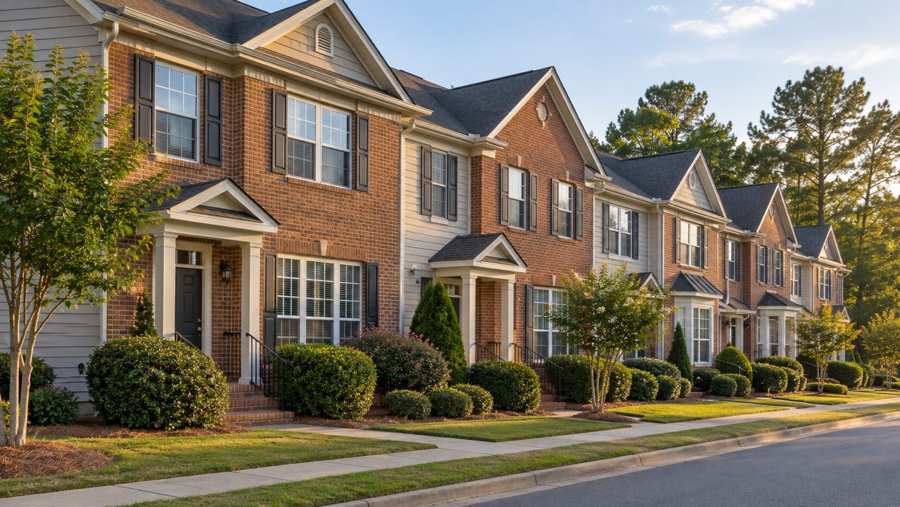
Selling an attached home near NoDa starts with a question that a street photograph cannot answer: what is the buyer actually acquiring? The building may look like a townhome while the recorded ownership is condominium. Parking may be deeded, a limited common element, an association assignment or a permit-based arrangement. Those differences affect how a seller describes the property and what needs review before an offer becomes dependable.
Prepare a dated file for the specific property, not a neighborhood-wide promise. The NoDa edge label here describes homes near the arts district, not a legal boundary or a separate association regime. Separate the recorded ownership, current dues and assessments, maintenance responsibilities, insurance coverage and parking documentation. North Carolina's statutory condo resale fee statement is narrower than a full practical review packet; gathering more useful records does not mean every document is required by that one provision.
Establish the Legal Ownership Before Advertising the Home
Begin with the deed, recorded declaration, amendments and applicable plans rather than the building's appearance. A townhome describes a building style, not one uniform ownership arrangement. Confirm whether the sale involves a condominium unit, fee-simple lot or another structure. Ask the closing attorney to explain the boundaries and associated rights before making statements about land, exterior responsibility or parking.
Mary Jo Burd's Charlotte Condos and Townhomes buyer guide says "A condominium is a legal form of ownership" and explains that a townhome can have different ownership structures. Use that distinction to frame the seller file, not to diagnose this property's regime from an address or exterior. The deed and recorded documents need to match the unit or lot being sold.
Ownership file: Keep the recorded instrument references, unit or lot identifier, relevant plans, amendments and current association contact together. North Carolina's Condominium Act Article Two explains creation by a recorded declaration and legal unit descriptions. Its reference to "the identifying number of the unit" shows why a marketing street address alone does not describe every legal interest.
Record whether a separate garage, storage interest or parking parcel is included and how it appears in the instruments. Do not describe common land as a private yard solely because one owner uses it. If the declaration, deed and manager's summary appear inconsistent, preserve the documents and seek professional interpretation rather than silently choosing the most favorable version for the listing.
Separate Private Parking Rights From Public Curb Access
Identify each space or parking arrangement and the document that supports it. Private ownership, limited-common-element allocation, revocable assignment and public on-street access are different claims. A numbered stall or routine use does not establish ownership or automatic transfer. Explain guest rules and transfer steps separately, and verify the actual street restrictions rather than promising unrestricted curb parking around NoDa.
The City of Charlotte Parking page says Park It manages on-street parking in "NoDa", among other named areas. Its residential permit section lists First Ward, Third Ward, Fourth Ward, Dilworth and Wilmore as current participating areas, not NoDa. That is a program description, not a finding that a specific block has no signs, meters or other restrictions.
North Carolina's Condominium Act Article Two says the declaration generally "shall specify to which unit or units each limited common element is allocated", subject to the section's exceptions. A parking allocation needs the applicable recorded provisions and amendments. The guide does not decide that a stall is a limited common element simply because it is marked with a unit number.
Parking sheet: Identify the space, legal or management basis, allowed vehicle uses, guest access, charges, enforcement rules and any transfer or registration procedure. Charlotte Living Realty's NoDa buyer article calls parking "block-dependent"; use its local question as a reason to verify the exact situation. Do not import another owner's agreement, an old permit or an informal arrangement as a permanent buyer entitlement.
Request a Current Association Packet Without Inventing a Statewide Package Rule
Ask the manager for the documents needed to understand current obligations and community issues. Keep the legal disclosure requirement separate from a practical review packet and from documents required by the chosen contract or lender. A product called a resale certificate is not automatically a comprehensive statutory certificate. Confirm the association, document date, covered property and any ordering or delivery procedures.
North Carolina's Condominium Act Article Four states that ordinary covered resale sellers must furnish a statement of "the monthly common expense assessment and any other fees payable by unit owners" before conveyance, with the provision's stated exceptions. This is not the declarant public-offering statement or a blanket full-package requirement. Applicability and additional duties need the actual transaction and professional review.
FirstService Residential's North Carolina resale certificate article says the state does not formally require a certificate "like other states" and distinguishes industry package terminology. Its practical explanation does not replace law, the owner's disclosure form or a contract's document obligations. A fee statement can be important without proving the association has no repairs, litigation, restrictions or funding concerns.
Practical packet: Request the declaration and amendments, bylaws and current rules, budget and available financial statements, reserve information, meeting minutes, insurance materials and assessment notices relevant to the sale. Ask which materials are current and what remains unavailable. Do not invent a universal ten-business-day delivery deadline or a standard package price from an online summary; confirm the manager's process and the applicable agreement.
Reconcile Dues, Special Assessments and Transfer Charges
Separate regular dues, approved changes, special assessments and transaction charges. Record the effective date, purpose, unpaid balance and any installment schedule using current association evidence. A dues figure in an old listing does not show the seller's current account or future obligations. Ask the closing attorney how the agreement allocates a particular charge rather than assuming the seller or buyer always pays it.
The North Carolina Real Estate Commission's current Residential Property and Owners' Association Disclosure Statement asks about changes "which have been duly approved" and fees connected with conveyance or transfer. Its owners' association section calls for information about each association when the form directs completion. Use the current July revision and professional advice about the actual disclosure responses, not a copied historical answer.
Mary Jo Burd's buyer guide cautions that "A lower monthly due is not always better" when funding is weak. That is a useful review principle, not proof that this association is underfunded. Compare the current budget, reserve evidence and actual project obligations instead of making the dues alone a selling point or automatically treating higher dues as a defect.
Cost ledger: List the payee, charge type, document date, amount, due date, remaining installments and unresolved allocation question. Distinguish an approved assessment from a discussed project or an estimate that has not been adopted. Keep manager-confirmed account information separate from a promise that nothing can change before closing; update the file when a new notice or adopted change arrives.
Identify Maintenance Boundaries and Completed Work
Map the responsibility for the actual component, then document the work and findings. A shared roof, exterior, balcony, water line or parking area may raise different maintenance and cost questions. Do not assume association responsibility means repairs are complete or free to owners. Keep the legal allocation, project scope, inspection findings and completion evidence separate so buyers can review the real issue.
North Carolina's Condominium Act Article Three describes the association's responsibility for common elements and says "Each unit owner is responsible for maintenance, repair and replacement of his unit" within its statutory structure. It also separates limited-common-element cost assessment. The actual regime, boundaries and applicable provisions matter; this is not a blanket promise that every attached-home exterior is maintained by an HOA.
Work history: Keep notices, engineer or specialist reports, proposals, board decisions, invoices and completion documentation organized by component and date. Distinguish recurring maintenance from an unresolved repair recommendation or a larger capital project. A recent invoice supports the work within its scope, not the condition of every connected system or a guarantee that a future assessment cannot occur.
Charlotte Living Realty's NoDa guide describes different housing and parking conditions across nearby blocks. Use that observation to avoid assuming newer infill and older attached buildings have the same ownership or maintenance questions. Share the actual property evidence with the professionals without diagnosing structural concerns from neighborhood age or presenting a visually tidy building as a completed project certification.
Prepare Insurance Documents Without Promising Lender Acceptance
Collect current association insurance documents and clarify what belongs to the owner. Policy periods, insured property, limits, exclusions and deductibles need qualified review. A master policy does not automatically cover all unit improvements or every owner's loss. Keep legal insurance duties, the owner's coverage decision and the buyer lender's requirements distinct; no generic guide can approve a policy or a loan.
Fannie Mae's Master Property Insurance Requirements page says the lender must review the policy and associated documents to "adequately evaluate the insurance coverage". That requirement belongs to its lending framework. A seller should provide useful current documents, not certify that a declarations page meets every possible loan program or that a cash buyer has no need to examine coverage.
North Carolina's Condominium Act Article Three addresses association insurance and specific coverage duties. Its statutory framework and a lender's eligibility standards serve different purposes. Ask the manager for the current policy information and the appropriate insurance professional about unit boundaries, improvements, coverage gaps, deductibles and loss-assessment concerns. Do not transplant an insurance percentage or deductible limit into an owner-wide legal rule.
Insurance file: Label the policy term and whether a renewal, cancellation, coverage change or unresolved claim affects the records being reviewed. Keep dated master documents alongside owner policy information where relevant. Ask for current evidence if the packet is stale, and avoid publishing an account-specific premium or coverage conclusion based only on the association's general assurances.
Distinguish Project Review From the Buyer's Individual Financing
A buyer's income approval does not necessarily settle condominium project eligibility. Shared building condition, assessments and insurance can affect a lender's review independently of the unit's presentation. Supply current evidence and ask the lender what remains needed for its actual loan. Avoid calling the entire community approved or ineligible based on a generic article, an old transaction or one owner's successful closing.
Fannie Mae's Ineligible Projects guide describes "material deficiencies and significant deferred maintenance" within its critical-repair rules. It identifies evidence such as meeting minutes, engineer reports, inspection reports, reserve studies and assessment lists that lenders may need. A seller should distinguish unaddressed critical repairs from routine work rather than label any assessment an automatic financing failure.
The same guide says that if an assessment relates to an unremediated critical repair, the project is ineligible under that rule. This does not make every assessment disqualifying or establish that this property has a critical repair. The lender must review the applicable program and actual documentation; an owner's description of a cosmetic project is not a lender finding.
Financing handoff: Ask which project questions are unresolved, which documents answer them and who is responsible for the next step. Keep the buyer's personal preapproval separate from association document review and the property's appraisal. If a prior buyer closed with another lender, treat that as transaction history, not a continuing approval or a promise that today's lender will use the same review.
Use Accurate Owner Disclosures and a Dated Record Table
Bring the current form and supporting records to the transaction professionals, keeping owner responses separate from broker duties and document review. Information about an association does not replace information about the property itself. Describe what is known and what needs confirmation without treating a No Representation response as proof that no issue exists. Update the packet when an actual change affects the sale.
The North Carolina Real Estate Commission's current disclosure form says owner responses "are not a warranty" and explains separate broker obligations. Its association section asks about charges, approved changes and specified litigation or violations involving the property. The exact form instructions, applicable exceptions and actual facts matter; neither a generic full-package checklist nor an as-is description determines every disclosure duty.
Record discipline: Date each document and distinguish a fact from an unresolved question. A manager's account statement answers a different question from a reserve study, recorded parking allocation or insurance policy. If one document conflicts with another, keep the conflict visible for review rather than selecting the version that makes the property sound cheaper or easier to transfer.
| Record | What it supports | What remains separate |
|---|---|---|
| Deed and recorded declaration | Ownership and boundaries | Building appearance |
| Parking allocation and rules | Documented space or use arrangement | Public curb availability |
| Current dues and assessment evidence | Dated financial obligations | Future funding guarantees |
| Work reports and completion evidence | Findings and documented project scope | All building condition |
| Master insurance and lender request | Coverage evidence and review questions | Loan approval |
| Disclosure and sale agreement | Owner responses and transaction terms | A universal resale package rule |
Compare Offers Using the Same Unresolved Questions
Compare written terms with the same association, parking and condition questions across buyers. An offer price does not reveal document contingencies, financing review, assessment allocation or transfer requirements. Ask the closing attorney to review what happens if a document is late, a charge changes or a claimed space cannot be conveyed as described. A faster proposed closing is not proof those issues disappear.
The National Association of Realtors' Real Estate Sales Contract Contingencies guide defines a contingency as "a condition that needs to be met" before completing the purchase. It includes association-document and financing review among possible terms. This general guide does not set the North Carolina contract's deadlines, create an automatic resale cancellation right or tell either party how its particular agreement operates.
Offer comparison: Ask for the purchaser identity, funding evidence, deposit, proposed dates, review conditions and allocation of identified charges. Separate the statute's ordinary resale fee statement from the declarant public-offering cancellation framework. Do not promise a seven-day ordinary resale rescission period simply because a new-condominium offering rule uses one; the actual sale and contract require review.
Better records can reduce avoidable uncertainty, but they do not guarantee a stronger price, lender acceptance or a completed sale. If the manager has not supplied a material item, describe what was requested and what remains missing. Let the professionals evaluate its consequence rather than call an empty folder a clean association or assume a buyer's cash claim settles title and parking rights.
Frequently Asked Questions
NoDa edge sellers should use the actual recorded ownership and current association records rather than the townhouse appearance or neighborhood label. Private parking rights are separate from public curb access. A condo resale fee statement is not a comprehensive project review, and loan approval, insurance, maintenance and contract terms each need their own evidence.
Does a townhouse exterior establish fee-simple ownership?
A townhome is a building style and may have different legal ownership structures. Review the deed, declaration and applicable plans with the closing attorney.
Does a marked parking stall automatically transfer?
A number or customary use does not establish the legal right or transfer process. Check recorded allocations, current rules and the actual arrangement.
Does NoDa have the same residential permits as Dilworth?
Charlotte currently lists several participating residential permit areas without naming NoDa. Verify the exact street restrictions and private parking rather than promise equivalent permits.
Is a full resale package required by the condo fee-statement provision?
The ordinary covered condo resale provision describes a statement of monthly common expenses and other owner fees. Additional disclosures, contracts and lender requirements must be considered separately.
Does a special assessment always block financing?
The purpose, project condition and applicable lending review matter. Fannie Mae distinguishes unremediated critical-repair issues from other circumstances rather than treating every assessment alike.
Does the association maintain everything outside my door?
Responsibility depends on the ownership regime, boundaries and applicable provisions. Common-element work, unit work and limited-common-element costs need separate review.
Does a master policy eliminate owner insurance questions?
The master documents do not settle every unit coverage or deductible question. Review current coverage with the appropriate insurance professional and actual lender requirements.
Does the resale fee statement create a seven-day cancellation period?
Do not import the declarant public-offering cancellation framework into an ordinary resale. Have counsel review the applicable transaction rules and signed contract.
Will Maison Off-Market solve missing association or parking records?
The described direct-sale process does not establish ownership rights or certify an association. Compare the actual written proposal and its handling of remaining questions with other sale options.
How Maison Off-Market Reviews a NoDa Edge Sale Option
Maison Off-Market describes a direct-purchase process that reviews a property before offering price and timing. A NoDa edge seller can compare its written option using ownership, association charges, maintenance, insurance and parking records. The company does not issue a lender project approval or change recorded rights. Confirm purchaser identity, conditions and charge allocation before relying on a proposed closing.
Maison Off-Market's homepage describes closing with "your attorney or title company", flexible dates, no commissions and no seller closing costs. Verify those statements in the actual property proposal, including net proceeds, deposit and any review conditions. A preference for no seller repairs does not erase association obligations, accurate property descriptions or transfer requirements.
Decision evidence: The actual proposal and written terms, not a verified NoDa association-resolution case study or a promised financing cure. Compare direct-sale and listing options with the same remaining records and charges. Ask what happens if the parking arrangement differs from the advertisement or current insurance and project information remains unresolved.
Compare your options before committing. Request a written private offer for your property, with no obligation, then weigh it against your listing plan.
Sources
- North Carolina General Assembly, Checked October 6, 2026. Condominium Act Article Two: Declaration, Boundaries and Limited Common Elements. https://ncleg.gov/EnactedLegislation/Statutes/HTML/ByArticle/Chapter_47C/Article_2.html.
- North Carolina General Assembly, Checked October 6, 2026. Condominium Act Article Three: Maintenance, Assessments and Insurance. https://www.ncleg.gov/EnactedLegislation/Statutes/HTML/ByArticle/Chapter_47C/Article_3.html.
- North Carolina General Assembly, Checked October 6, 2026. Condominium Act Article Four: Resales and Public Offering Rules. https://www.ncleg.gov/EnactedLegislation/Statutes/PDF/ByArticle/Chapter_47C/Article_4.pdf.
- North Carolina Real Estate Commission, Checked October 6, 2026. Residential Property and Owners Association Disclosure Statement, July Revision. https://www.ncrec.gov/Forms/Consumer/rec422.pdf.
- City of Charlotte, Checked October 6, 2026. Parking: Park It and Residential Permit Program. https://www.charlottenc.gov/Streets-and-Neighborhoods/Parking-and-Streets/Parking.
- Fannie Mae, Checked October 6, 2026. Ineligible Projects: Critical Repairs and Project Evidence. https://selling-guide.fanniemae.com/sel/b4-2.1-03/ineligible-projects.
- Fannie Mae, Checked October 6, 2026. Master Property Insurance Requirements for Project Developments. https://selling-guide.fanniemae.com/sel/b7-3-03/master-property-insurance-requirements-project-developments.
- Mary Jo Burd, Checked October 6, 2026. Charlotte Condos and Townhomes: A Buyer Guide. https://maryjoburd.com/blog/charlotte-condo-and-townhome-living-what-buyers-should-know.
- Charlotte Living Realty, Checked October 6, 2026. What To Know Before Buying in NoDa Charlotte. https://charlottelivingrealty.com/blog/what-to-know-before-buying-in-noda.
- FirstService Residential, Checked October 6, 2026. A Guide to Your North Carolina Resale Certificate. https://www.fsresidential.com/north-carolina/news-events/articles/north-carolina-resale-certificate/.
- National Association of Realtors, Checked October 6, 2026. Real Estate Sales Contract Contingencies. https://www.nar.realtor/the-facts/consumer-guide-real-estate-contract-contingencies.
- Maison Off-Market, Checked October 6, 2026. Homepage: Direct-Purchase Process and Stated Terms. https://bulkscaler.com.
Related research
Seller Guide · 2026-10-08
How to Prepare Bloomfield Hills Tree and Woodland Sale Records
Separate tree approvals, replacement duties and wetland limits before selling wooded property.
Seller Guide · 2026-10-07
How to Prepare Georgetown Historic Exterior Sale Records
Separate historic design approval, building permits and actual exterior work before selling.
Seller Guide · 2026-10-07
How to Prepare Tenafly Tree Permit Sale Records
Connect tree removal approvals, mitigation planting and accepted inspections before promising landscape changes.