Seller Guide · by Aidan Sowa · October 6, 2026
How to Prepare Newport Center Condo Insurance Records Before Selling
Match the master policy, unit coverage and repair records before comparing sale options.
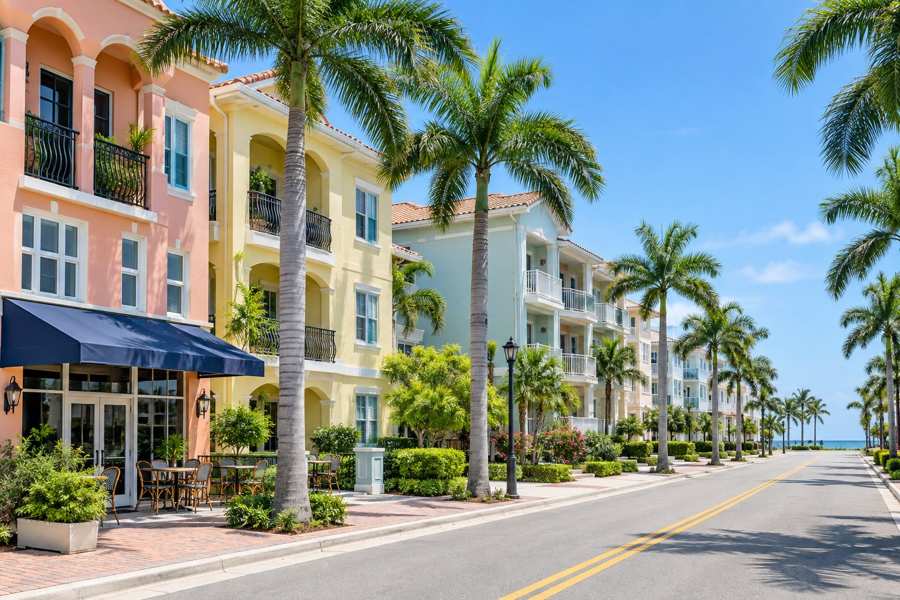
A Newport Center condominium sale can stall when a buyer asks what the association's insurance actually covers and the seller has only a summary. California Legislative Information's Civil Code section 5300 requires the annual budget report 30 to 90 days before the end of the fiscal year and requires an insurance summary. The same statute warns that the summary is not a substitute for the complete policy.
This guide is for an owner selling a condominium in or near Newport Center, not for every home in the postal area and not for a tenant selling an apartment interest. It shows how to match the association master policy, unit-owner coverage, renovations, repair costs and buyer financing questions. The result is a clearer record handoff, not a promise that a buyer can obtain coverage or a particular mortgage.
What the Condo Insurance File Actually Covers
A condo insurance file connects the legal unit boundaries with association coverage and the owner's separate policy. It should identify who insures which property, which deductibles may apply and what records support improvements or prior repairs. Start with this building's governing documents and current policies, not another nearby building's marketing brochure or a neighborhood-level insurance assumption.
The City of Newport Beach's Residences at Newport Center Planned Community Development Plan describes a specific 28-unit condominium project at Newport Center Drive and Anacapa Drive. That is planning context for one site, not proof of completed inventory, occupancy or common insurance terms across Newport Center. It illustrates why the actual legal project and unit matter more than a district name.
Identify the insured interest: Keep the condominium plan, declarations, association name, unit designation and any parking or storage rights together. Ask the title and association professionals which spaces are part of the separate interest, common area or exclusive-use common area. A private-looking balcony or garage does not itself settle ownership, maintenance responsibility or the insurance treatment of the space.
The California Department of Insurance's Residential Insurance guide, revised January 2026, explains that unit-owner insurance includes interior and improvement coverage for property the owner is responsible for under the governing rules. It says the association generally insures the building structure and common areas. The word "generally" matters: obtain the actual policies and documents before telling the buyer the association covers everything beyond the front door.
How to Read the Master Policy Beyond the Summary
Read the current master-policy declarations, coverage forms and endorsements together, with an insurance professional explaining limits, exclusions and deductibles. Use the statutory summary as the index to those documents rather than as proof of complete protection. Confirm effective dates and renewal status, and distinguish property insurance from liability, earthquake, flood and fidelity coverage.
Civil Code section 5300 requires a summary of the association's property, general liability, earthquake, flood and fidelity policies, including insurer, policy type, limit and deductible if any. It permits specified information on a declaration page to meet the disclosure requirement. That does not turn the declaration page into the whole contract or establish that every listed category has unlimited protection.
The statute's required warning says the summary "should not be considered a substitute" for complete terms. It also warns that association policies may not cover an owner's property, improvements or certain losses and that an owner may still owe part of a deductible. Owners may review association policies on reasonable notice and request copies subject to reasonable duplication charges under that provision.
Policy checklist: Record the named insured, covered property, policy period, limits, applicable endorsements and deductible wording. Ask whether the document received is the present policy or last year's version, and whether a renewal or nonrenewal notice changes the sale timeline. Keep a broker's explanation attributed and dated. Do not translate a summary line reading property insurance into a guarantee that a particular water, roof or earthquake loss will be paid.
Match Unit Coverage to the Interior and Improvements
Match the unit-owner policy to the parts of the interior and improvements the master policy does not cover. Retain renovation details and ask a licensed insurance professional to identify gaps, limits and covered perils. The buyer needs coverage for the buyer's own interest and timing; the seller's existing policy is evidence of past arrangements, not an automatically transferred contract.
The Department of Insurance's Residential Insurance guide describes condo unit-owner coverage for personal property, loss of use, liability and medical payments, as well as specified interior and improvement damage. It advises owners to "Keep accurate records" of updates, renovations and improvements and discuss modifications with the insurer. For a renovated condo, cabinets, flooring and fixtures should be documented rather than valued from a listing photograph.
Fannie Mae's Selling Guide topic B7-3-04 says a unit-owner policy is required for covered loans when the master policy does not cover part of the interior or improvements, or when the master policy has a per-unit deductible. The topic describes coverage sufficient for uncovered interior or improvements and the per-unit deductible, using the greater applicable amount. The lender and insurance professional must apply the current requirements to the actual loan and policies.
Describe the gap, not a product slogan: Labels such as walls-in or all-in do not replace the policy language. Assemble the inventory of owner improvements, receipts where available, association boundary rules and master-policy scope. Ask the buyer's insurance professional what can be quoted and when coverage can begin. Do not promise that the seller's premium, limits or insurer availability will carry over to the new owner.
Keep Deductibles and Assessments in Different Columns
A deductible, an approved special assessment and a possible future repair cost are different obligations. Ask how a covered loss is adjusted, who may be allocated a deductible and what the owner policy would actually pay. Keep existing account charges and approved future charges separate from estimates or budget discussions. A large policy limit does not eliminate these questions.
Fannie Mae's March 18, 2026 Lender Letter LL-2026-03 updates the maximum allowable master-policy per-unit deductible for required property perils to $50,000 per unit, with mandatory application to loan application dates on or after July 1, 2026. That is a loan-eligibility rule within its scope, not this building's actual deductible, a universal insurance-law ceiling or evidence that the buyer has coverage for the amount.
The same letter says a borrower needs a unit-owner policy when the master policy has a per-unit deductible, described in the letter as "per unit deductible", and directs coverage sufficiency to the greater of the uncovered interior or improvement amount and the per-unit deductible amount. Do not calculate a needed policy by dividing a building-wide deductible by the number of units unless the actual documents and responsible professionals support that allocation.
California Legislative Information's Civil Code sections 4525 and 4530 provide the transfer-document framework for current regular and special assessments, unpaid owner obligations and specified approved changes not yet due. Request the actual account statement and notices. A clean current balance does not prove there are no approved future charges, and an insurance discussion in board minutes does not by itself prove a new assessment has been levied.
Separate Earthquake Coverage From General Loss Assessment Coverage
Ask specifically whether the association and unit owner have earthquake coverage and how any assessment-related coverage works. Do not assume a standard residential policy covers earthquake damage or that a loss-assessment endorsement pays every special assessment. Covered causes, exclusions, limits and deductible treatment must be checked in the actual contracts before describing protection to a buyer.
The California Department of Insurance's Earthquake Insurance guide explains that ordinary homeowners, renters and condominium policies do not cover earthquake damage and that separate coverage may protect belongings, living expenses and certain assessment obligations. It tells condo owners to "Talk to your condo association" about their situation. This is a prompt to investigate, not a finding that a particular association has earthquake insurance.
The guide says the association may require owners to share repair costs or a policy deductible through an assessment. Its discussion of California Earthquake Authority condo policies describes up to $100,000 for a share of certain assessments imposed for covered earthquake damage. That is a description of that product's potential coverage, not the seller's policy limit or an assurance that all assessments qualify.
Questions for the broker: Which peril caused the loss, which contract responds, what limit applies and is a master-policy deductible within the purchased coverage? Also ask about loss of use and the period it covers. Routine maintenance, a reserve shortfall and insured damage are not interchangeable categories. Keep the answers with the policy wording and avoid describing loss-assessment coverage as insurance against all future dues increases.
Connect Repair Responsibilities to Actual Work Records
Use the declaration and current law to identify maintenance and repair responsibilities, then connect each known repair to its approval, permit and completion records. A policy does not decide every maintenance obligation, and association approval does not certify a City final inspection. Keep claim payments, contractor work and written completion decisions as separate records with clear dates.
Civil Code section 4775, as currently published by California Legislative Information, states default responsibility rules subject to the declaration: the association repairs, replaces and maintains common area; the owner handles the separate interest; and exclusive-use common-area maintenance and repair or replacement are treated differently. It also includes current provisions for interrupted utility services beginning in common area. Do not quote an old shorthand that omits those provisions or overrides this building's declaration.
The current section 4775 utility provision calls for the board to "commence the process" to make the repairs within 14 days of interruption for specified services within its scope. Commencing that process is not a promise that every repair will be finished within fourteen days. The statute also addresses temporary relocation costs and financing under specified circumstances, so ask counsel about applicability rather than inventing a simple allocation for every leak or outage.
Civil Code section 4765 addresses written association decisions when governing documents require approval of physical changes. The City of Newport Beach's Permit History by Address page separately distinguishes completed archives and open projects and warns of limits in online searches. Its iPermit page provides the online permitting route. Match the actual work to both systems, and do not treat an insurance payout or contractor invoice as proof of final approval by either authority.
Read Reserve and Inspection Records Without Promising Future Costs
Reserve studies, budgets and inspection reports help explain known building needs, but they do not guarantee future assessments or insurance pricing. Distinguish adopted charges, projected funding gaps and documented repair findings. Request the records applicable to the actual association and building, and ask qualified professionals to interpret structural or waterproofing issues rather than summarizing them as harmless because the unit looks new.
Civil Code section 5550 requires a reasonably competent and diligent visual inspection of accessible major components as part of a reserve study at least every three years, when their current replacement value reaches at least one-half of the gross association budget excluding reserves. It requires annual review of the study and consideration of adjustments. The threshold and accessible-area scope matter; the rule is not a guarantee that every concealed component has been inspected.
Civil Code section 5570 provides the assessment and reserve funding disclosure summary, separating scheduled approved charges from additional contributions projected to be needed. Its note says "The estimates are subject to change" and identifies assumed interest and inflation rates. A percentage-funded figure therefore belongs with the component list, assumptions and funding plan, not alone in a sale description as proof the building cannot face a special assessment.
Civil Code section 5551 covers qualifying condominium projects and specified association-maintained exterior elevated elements, with wood or wood-based load-bearing components, height and building criteria. It is not a blanket inspection rule for every balcony in every concrete or steel building. Section 4525 includes the most recent report under that provision where applicable. Have the association identify applicability and provide the actual report, findings and repair status instead of inferring structural safety from architecture photographs.
Prepare for Buyer Financing Without Certifying the Project
Provide current association and policy records early enough for the buyer's lender to review, but leave loan eligibility to that lender. Requirements depend on the loan program, project type and application date. A conforming-loan rule is not a universal rule for a cash purchase or every lender, and a passing insurance review does not settle all project-review conditions.
Fannie Mae's Selling Guide topic B7-3-03 describes master-property insurance requirements for condo projects whose loans it purchases, subject to the project's legal-document and individual-policy provisions. The lender verifies required coverage. Keep the master declarations and endorsements ready with the association questionnaire and relevant budget and repair records. Do not label a building Fannie-approved merely because it carries a master policy.
Lender Letter LL-2026-03 describes "Retirement of the Limited Review process" for loan applications dated on or after August 3, 2026, and makes changes to reserve-study flexibility on that application-date schedule. Its increased reserve-allocation requirement of 15%, instead of 10%, applies to Full Review loan applications dated on or after January 4, 2027. That future effective date must not be rewritten as an already mandatory October rule for every condo sale.
The letter also revises insurance requirements, including master-policy roof loss-settlement treatment and per-unit deductibles. Because requirements and implementation dates change, ask the lender which current provisions it is using for the application. A different loan program may reach a different result. If financing is an offer condition, put any required document delivery and review period in the written agreement rather than promising approval in the marketing material.
Compare Sale Routes With the Same Insurance Facts
Compare a listing and a private offer using the same known policy, repair and assessment facts. Identify which questions can be answered with documents, which need professional interpretation and which remain unresolved. Use written terms for timing, conditions and allocation of responsibilities rather than assuming a cash buyer makes policy gaps or seller disclosure obligations disappear.
File handoff: The comparison below is a record-planning tool based on the Department of Insurance, current California Civil Code, City permit guidance and Fannie Mae's published loan requirements. It is not a quote, policy recommendation or prediction of a buyer's loan result. The seller can improve clarity without choosing the buyer's insurer or guaranteeing underwriting.
For example, a renovated unit with a master summary but no policy endorsements needs a scope review before the seller claims the upgraded interior is covered. A documented water-loss repair needs the work and completion evidence as well as the claim paperwork. A pending renewal should be described by its actual written notice and timing, not converted into an assumed affordable premium for the next owner.
Compare the net proceeds, closing and possession timing, conditions and treatment of unresolved assessment or repair records in the actual offers. Keep applicable disclosures and title matters in the plan even if a buyer does not use a mortgage. For nearby but distinct parcel issues, the Dover Shores record guide explains why neighborhood labels cannot substitute for documented association rights.
| Question | Record to collect | Who reviews | Avoid this promise |
|---|---|---|---|
| What does the HOA insure? | Master policy and endorsements | Association insurance professional | The summary covers every loss |
| Are upgraded interiors covered? | Unit policy and improvement inventory | Licensed insurance professional | Seller coverage transfers automatically |
| Who pays a deductible? | Policy wording and allocation documents | Insurance and legal advisers | Every assessment is insured |
| Are repairs complete? | Approval, permit and final work records | Association and City professionals | Claim payment proves completion |
| Will a loan work? | Current project, budget and policy records | Buyer lender | One policy proves project eligibility |
Frequently Asked Questions
These questions address the insurance and repair gaps that can surface during a Newport Center condo sale. Answers separate current policy evidence from summaries and lender rules from universal obligations. They do not determine coverage for a particular building, unit or loss, and they do not replace an insurance professional's or lender's review of the actual documents.
Does the association insurance summary prove my whole unit is covered?
No, Civil Code section 5300 warns that the summary is not a substitute for complete policy terms. Review the current policy, endorsements, boundaries and owner coverage with an insurance professional.
Can the buyer just take over my condo insurance?
Do not assume the seller's policy or premium transfers to a new owner. The buyer needs confirmation of coverage for the buyer's own interest and effective date.
What records help explain upgraded cabinets and flooring?
Keep improvement descriptions, receipts where available and relevant approval and completion records. Match those improvements to the master and unit-policy scope rather than assuming the original building coverage includes every upgrade.
Does loss-assessment coverage pay every special assessment?
No, coverage depends on the insured cause, limits, exclusions and actual contract wording. Routine maintenance charges and reserve shortfalls should not be treated as guaranteed insured losses.
Is the association guaranteed to have earthquake insurance?
No, the Department of Insurance tells condo owners to investigate association and separate earthquake coverage. Obtain the actual policy information instead of inferring it from ordinary property coverage.
Does the fourteen-day utility rule mean repairs must be finished then?
No, current Civil Code section 4775 describes commencing the repair process for specified interrupted services within its scope. Applicability and completion depend on the actual situation and governing documents.
Does every Newport Center balcony need the same inspection report?
No, Civil Code section 5551 has project, component, responsibility, height and building criteria. Ask the association which requirements apply and obtain the relevant report and repair status.
Is a fifteen-percent reserve allocation already required for every sale?
No, the March 2026 Fannie Mae letter makes that change mandatory for Full Review loan applications dated on or after January 4, 2027. The buyer's lender must identify the loan program, application date and current requirements.
Can selling for cash remove insurance and disclosure questions?
A cash sale may remove a mortgage underwriting step, but it does not itself cancel applicable seller disclosures or association obligations. Compare written terms and known records with the appropriate transaction advisers.
How Maison Off-Market Fits a Condo Record Handoff
Maison Off-Market offers a direct-sale route that can be compared with a listing after the condo records are organized. Its public site describes a private offer process and seller-facing benefits. Those claims do not certify insurance coverage, waive association obligations or establish that every condominium fits its purchase criteria, so the property-specific written offer remains the decision document.
Maison Off-Market's public website says it buys luxury homes and estates directly from owners and describes no showings, no commissions, no closing costs and no seller repair work. It explains that the property and land are assessed and a direct offer follows if the property fits. This guide has not reviewed a purchase offer, private insurance contract or completed local condo acquisition, so it does not promise eligibility or a particular price.
Compare written terms: Provide the same known master-policy, unit, assessment and repair information used for the listing alternative. Ask what the offer requires, who will obtain missing records and how any unresolved obligations affect net proceeds or timing. A quieter sale process may be useful, but it is not proof that incomplete coverage or an unfinished building repair no longer matters.
Compare your options before committing. Request a written private offer for your property, with no obligation, then weigh it against your listing plan.
Sources
- City of Newport Beach, Public planning document checked October 2026. Residences at Newport Center Planned Community Development Plan. https://www.newportbeachca.gov/PLN/MAP_DOCUMENTS/PC_TEXT/PC_61_Residences_at_Newport_Center.pdf.
- California Department of Insurance, Revised January 2026. Residential Insurance: Homeowners and Renters. https://www.insurance.ca.gov/01-consumers/105-type/95-guides/03-res/res-ins-guide.cfm.
- California Department of Insurance, Current page checked October 2026. Earthquake Insurance. https://www.insurance.ca.gov/01-consumers/105-type/95-guides/03-res/eq-ins.cfm.
- California Legislative Information, Current text checked October 2026. Civil Code section 5300 annual budget and insurance disclosures. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=CIV§ionNum=5300.
- California Legislative Information, Current text checked October 2026. Civil Code section 4775 maintenance, repairs and utilities. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=CIV§ionNum=4775.
- California Legislative Information, Current text checked October 2026. Civil Code section 5550 reserve studies. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=CIV§ionNum=5550.
- California Legislative Information, Current text checked October 2026. Civil Code section 5570 reserve funding disclosure. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=CIV§ionNum=5570.
- California Legislative Information, Current text checked October 2026. Civil Code section 5551 exterior elevated elements. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=CIV§ionNum=5551.
- California Legislative Information, Current text checked October 2026. Civil Code transfer disclosure sections. https://www.leginfo.legislature.ca.gov/faces/codes_displayText.xhtml?article=2.&chapter=4.&division=4.&lawCode=CIV&part=5.&title=.
- California Legislative Information, Current text checked October 2026. Civil Code modification of separate interest sections. https://leginfo.legislature.ca.gov/faces/codes_displayText.xhtml?article=2.&chapter=5.&division=4.&lawCode=CIV&part=5.&title=.
- Fannie Mae, Current topic checked October 2026. Master Property Insurance Requirements for Project Developments. https://selling-guide.fanniemae.com/sel/b7-3-03/master-property-insurance-requirements-project-developments.
- Fannie Mae, Current topic checked October 2026. Individual Property Insurance Requirements for a Unit in a Project Development. https://selling-guide.fanniemae.com/sel/b7-3-04/individual-property-insurance-requirements-unit-project-development.
- Fannie Mae, March 18, 2026. Lender Letter LL-2026-03: Project Standards and Property Insurance Requirements. https://singlefamily.fanniemae.com/media/44986/display.
- City of Newport Beach, Current page checked October 2026. Permit History by Address, Modifications. https://www.newportbeachca.gov/government/data-hub/online-services/permit-plan-check-information/permit-history-by-address-modifications.
- City of Newport Beach, Current page checked October 2026. Online Permitting iPermit. https://www.newportbeachca.gov/government/departments/community-development/building-division/online-permitting-ipermit.
- Maison Off-Market, Public page checked October 2026. Direct home purchase service claims. https://bulkscaler.com.
Related research
Seller Guide · 2026-10-08
How to Prepare Bloomfield Hills Tree and Woodland Sale Records
Separate tree approvals, replacement duties and wetland limits before selling wooded property.
Seller Guide · 2026-10-07
How to Prepare Georgetown Historic Exterior Sale Records
Separate historic design approval, building permits and actual exterior work before selling.
Seller Guide · 2026-10-07
How to Prepare Tenafly Tree Permit Sale Records
Connect tree removal approvals, mitigation planting and accepted inspections before promising landscape changes.