Seller Guide · by Aidan Sowa · October 6, 2026
How to Prepare Sedona Wildfire Mitigation and Insurance Records
Document completed risk-reduction work and actual coverage before comparing sale terms.
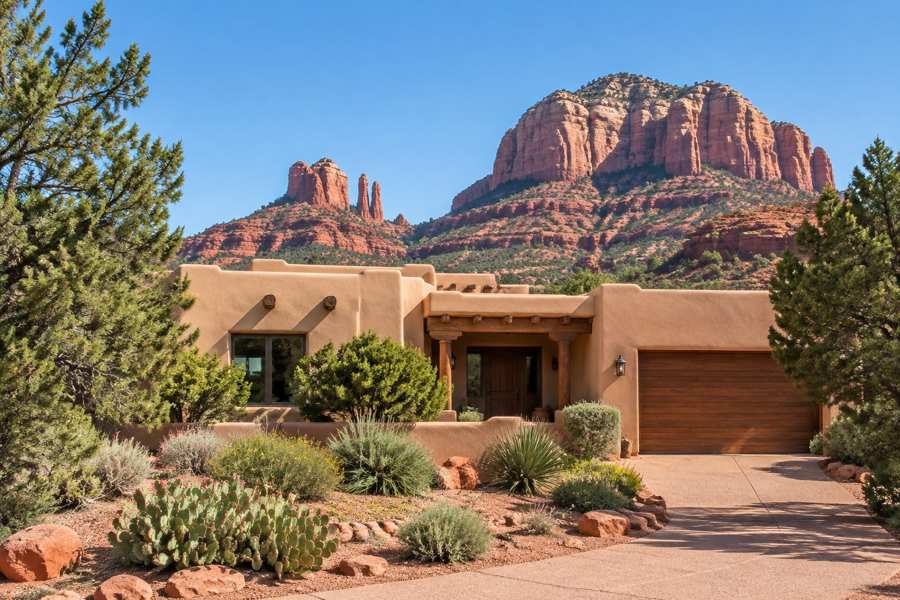
A Sedona seller can show completed wildfire-risk work without calling the home fireproof or promising a buyer affordable insurance. The useful file separates local fire guidance, vegetation maintenance, structure-level improvements, a voluntary designation and the insurer's actual response. A trimmed yard or community sign does not answer every one of those questions.
IBHS's current Wildfire Prepared Home FAQ requires a continuous zero-to-five-foot noncombustible zone for its designation. That is a specific voluntary-program requirement, not a blanket statement that every Sedona parcel has the same legal clearing rule. The program became available in Arizona in April 2026, and its current materials distinguish Essential and Enhanced levels. Confirm the actual property and chosen standard before paying for work or an application.
This guide applies Sedona Fire District, IBHS, NFPA and Arizona insurance sources alongside substantive local professional articles. It explains how to prepare assessment notes, photos, permits, maintenance records, certificates and coverage questions before comparing a listed sale with a private proposal. Risk reduction is useful evidence, not proof that a fire cannot damage the house or that an insurer must accept it.
Separate Community Firewise Work From the Condition of the House
Firewise community recognition, defensible space, structure hardening and insurance review answer different questions. Dennis Riccio's Central Arizona Association of REALTORS article explains the community-versus-structure distinction and advises documenting work instead of guaranteeing safety. Apply that framework in Sedona without importing another community's local rules. A recognized neighborhood can still contain a house with vulnerable vents, roof debris or combustible materials beside its walls.
Community evidence: Keep the recognized site's identity, current participation information and relevant community assessment or action-plan materials. NFPA describes Firewise USA as a voluntary recognition framework for neighbors working together. That record does not certify every individual structure, establish the condition of this roof or grant the buyer an insurance policy. Verify the actual community rather than assuming a nearby recognized development includes the parcel.
Sedona Fire District offers Firewise planning and inspections for homes or communities. A seller can request guidance through Community Risk Reduction and retain the dated recommendations. Keep that assessment separate from municipal permit inspections and from an IBHS designation evaluation. A recommendation to improve a feature is not a certificate saying the feature has already been improved.
Plain description: Say which documents the seller has supplied and which work was completed. Riccio's article recommends observable facts, receipts and referrals rather than 'fire safe,' 'fireproof' or 'guaranteed insurable.' Sedona's local real estate Firewise article also encourages vegetation maintenance and home hardening; use those categories while confirming technical requirements with the actual authority and program.
Confirm the Parcel and Applicable Fire Review
Confirm the property, fire district and WUI review with the responsible authority before treating a regional map as the answer. Sedona Fire District's current development page separates its fire code, WUI code, permit review and public guidance. Adobe Group's seller article recommends organizing jurisdiction, permits and site records early. Apply that records-first approach instead of assuming a Sedona mailing address establishes every rule for the property.
Current authority: The district's development page states that its amended 2024 International Fire Code was adopted April 21, 2026 and became effective May 1, 2026. It separately identifies adoption of the amended 2018 WUI code in November 2021. The newer fire-code adoption is not evidence that every separate WUI provision was replaced; confirm which code and policy govern the actual proposed work.
The district says additions and new construction go through plan review and permitting. A roofing, vent, fence, deck or access project may also involve building, fire, HOA or other review according to its scope. Ask the responsible offices and qualified contractor before work begins. A voluntary mitigation checklist should not be used as permission to change a building feature or remove protected vegetation.
Parcel record: Keep the address, parcel number, governing jurisdiction, relevant WUI information and written staff guidance. A hazard map can identify a review topic but does not inspect the structure or bind an insurer's model. Record when a map or assessment was checked and have the actual access, terrain and improvements evaluated without declaring one property low risk from a regional color alone.
Create a Dated Mitigation Inventory Before Ordering More Work
Start with what exists, what was recommended and what was completed. Esther Talbert's Yavapai Realty article recommends before-and-after photographs, receipts, checklist notes and insurance questions. Apply that documentary approach rather than presenting an intended cleanup as finished mitigation. Separate vegetation and debris maintenance from roof, vent, deck or fence improvements, and record outstanding items so the buyer and professionals can assess the actual property.
Work ledger: Record the feature, location, completion date, contractor or responsible person, invoice and supporting photograph. Include the assessor's or mitigation professional's recommendation when one exists. Label owner-reported work, inspected work and program-verified work differently. A landscape invoice may document brush removal but not the installation quality of an ember-resistant vent or the fire rating of the roofing assembly.
Retain product information and installation records for structure-level changes, with applicable permits and inspection results. Ask the relevant professional what evidence supports a claimed roof classification or vent performance. A metal-looking roof, stucco exterior or small vent opening visible in a photograph should not be treated as verified compliance with a technical standard. The installed system and its details matter.
Current photographs: Show the same areas before and after work, then update photos when conditions change. Include attached decks, fence connections, roof and gutter condition where safely documented, and the ground next to the structure. Do not climb onto an unsafe roof for sale photographs; use a qualified service provider. A seller file should explain what was checked without creating another safety risk.
| Record | What it supports | What it does not prove |
|---|---|---|
| Community recognition | Organized neighborhood participation | Each house meets a parcel standard |
| Firewise assessment | Dated recommendations | Recommended work is completed |
| Receipts and photos | Specific completed tasks | Every technical requirement is met |
| IBHS certificate | Program designation and status | Guaranteed coverage or fire survival |
| Insurer response | Actual terms or requested evidence | Another buyer receives the same offer |
Review the Immediate Zone Without Assuming Native Plants Are Exempt
For an IBHS home designation, the zero-to-five-foot zone must be continuous and noncombustible under the current requirements. Its FAQ says cactus, succulents, irrigated plants, grass, artificial turf and wood mulch are not exceptions within that zone. Apply the official rule to the chosen program rather than copying a generic fire-resistant landscaping list. Legal restrictions, property boundaries and HOA approvals still need review before changing the site.
Program-specific scope: The FAQ explains that measurement depends on exterior walls and certain attached structures. Have the program materials and a qualified professional guide the actual layout, including decks or patios. Do not simply measure from a convenient garden edge. A favorable photograph of one side of the house does not establish a continuous zone around the full structure.
IBHS says protected trees that cannot legally be removed within the required zone may affect eligibility. It also describes coordination where the property line is less than five feet away. The designation does not grant access to neighboring land or override legal vegetation protection. Obtain the necessary permission and authority guidance; if the requirement cannot be met, record that limit rather than inventing a program exception.
Maintenance distinction: Removing combustible stored items and accumulated debris is different from permanent alterations or clearing beyond the property. Have the assessor address vegetation farther from the home according to the site and governing rules. Do not treat the local broker's broad thirty-foot or driveway advice as a universal legal specification, and do not promise that any particular plant cannot burn.
Use the Current IBHS Requirements and Actual Designation Status
IBHS announced Arizona program availability in April 2026 and updated its home requirements and level names in June. Its current FAQ requires every action for the chosen designation and says partial mitigation does not qualify. Keep the current checklist, application, evaluation, corrections and issued certificate together. An application payment, a contractor's marketing claim or use of an older checklist is not evidence that the home holds an active designation.
Eligibility and cost: The FAQ describes eligible homes on permanent foundations with three stories or fewer above grade and compliance with applicable WUI codes. It identifies eligible dwelling categories and excludes homes under active construction. The current application fee is $125 and nonrefundable, separate from mitigation costs. Confirm the actual property with the program before assuming a detached home automatically qualifies.
The current technical-standard page identifies the approved update effective June 1, 2026. The June announcement uses Essential, formerly Base, and Enhanced, formerly Plus. Retain the level and requirements used for the actual evaluation. A certificate from an earlier evaluation should be reviewed for its present status and maintenance obligations rather than relabeled as if a later standard was necessarily applied.
Evaluation result: Keep requested corrections, resubmitted evidence and final approval. The FAQ describes timelines that depend on readiness and evaluator availability and says expedited scheduling is unavailable. Plan for the actual process rather than promising a certificate before a listing launch or closing. If work is incomplete, market the documented improvements without presenting the house as designated.
Maintain the Record and Confirm Certificate Transfer Separately
A designation remains useful only if its required conditions and status are maintained. IBHS's FAQ says home designations are valid for three years with photo-based annual review after the first year and in year two. It also permits certificate transfer to a new homeowner for a fee. That process concerns a property designation, not automatic assignment of insurance, building approvals or the seller's other service agreements.
Current status: Keep the certificate, designation date, renewal information, annual reviews and any outstanding requests. Later landscaping or combustible storage within the required zone can jeopardize status. A seller should identify changes since evaluation and check them with the program rather than relying on the certificate's original issue date as proof that present conditions are unchanged.
The FAQ says the new owner can create an account and request transfer after closing for a small fee; it does not give a universal transfer price in that explanation. Confirm the actual steps and fee with the program. Do not promise that handing over a PDF alone completes the transfer or that the seller's account credentials should be given to the buyer.
Ownership plan: Identify who will maintain landscaping and debris control during vacancy, travel or the sale period. Keep dated work and review reminders with the file. A property can accumulate debris after photography or lose maintenance continuity while ownership changes. Use current evidence to describe the remaining duties rather than presenting designation as a permanent one-time upgrade.
| Question | Evidence to check | Remaining decision |
|---|---|---|
| Is work complete? | Assessment, receipts and current photos | Professional review of gaps |
| Is there a designation? | Issued certificate and active status | Program confirmation where unclear |
| Is it maintained? | Annual review and current conditions | Corrections or renewal needed |
| Will it transfer? | Program ownership-change instructions | Buyer transfer process and fee |
| Will insurance be available? | Address-specific insurer response | Actual policy terms and binding |
Ask the Insurer What Evidence Matters for This Address
Send the insurer or licensed agent the actual mitigation evidence and ask what they will review. Yavapai Realty recommends specific questions about work, certificates and underwriting response rather than promising a discount. IBHS says discounts vary and are not guaranteed. Arizona DIFI encourages active shopping and understanding policy terms. The seller's current premium and a community's Firewise participation do not establish the purchaser's future coverage or cost.
Insurance file: Retain the declarations, relevant endorsements, renewal or nonrenewal notice, inspection requests and written responses. Protect unrelated personal information when sharing the transaction file. Ask what roof, vegetation, access or other facts the insurer used and whether corrected information or additional mitigation evidence can be reviewed. A submitted document should not be recorded as accepted until the insurer responds.
DIFI's consumer guide distinguishes replacement cost from market value and actual cash value. Compare coverage limits, deductibles, exclusions and loss-of-use provisions as well as the premium. A lower-priced policy may have a different deductible or narrower coverage. A seller's asking price is not a replacement-cost estimate, and a home warranty does not replace catastrophe insurance.
Buyer-specific decision: Have the purchaser obtain an address-specific review for the intended use, ownership and effective date. Identify whether the insurer's response is an indication, conditional quote or coverage actually bound. Keep insurance review and the sale contract's contingencies aligned with professional advice. Do not describe mitigation as an obligation for every carrier to insure the property or renew the seller's policy.
Keep Maintenance, Access and Emergency Planning in the Handoff
Maintain vegetation and structure-level work while keeping access and emergency planning separate from insurance certification. Sedona Fire District offers local education, Firewise inspections and current burn-status information. Use the district's guidance for the actual site and season. A cleanup receipt does not authorize burning, establish fire-apparatus access or replace the household's evacuation plan. Record ongoing duties instead of treating mitigation as finished forever.
Service records: Include roof and gutter cleaning, debris removal and relevant landscape maintenance, with actual dates. Have the appropriate professional review decks, fence connections and recurring vegetation issues. Seasonal or second-home use may require a reliable maintenance arrangement while the owner is away. Do not invent a universal cleaning interval; record the assessment recommendations and actual condition.
The district separately publishes access and water-supply guidance and oversees fire-related permits. If a gate, drive, address sign or proposed improvement raises an access issue, ask Community Risk Reduction which standards apply. Do not use a broker's twelve-foot driveway suggestion as official approval for this parcel. A community's fire-protection classification is also a different measure from a property's wildfire-ignition risk or carrier underwriting.
Disposal and emergency readiness: The district directs residents to current burn status and restrictions; its spring cleanup is an event, not a guaranteed year-round disposal service. Confirm the current permitted disposal method rather than burning yard waste based on an old seasonal description. For household safety, use local emergency-management directions and a current evacuation plan, not the sale file as a substitute for emergency instructions.
Compare Sale Proposals Without Pricing a Guaranteed Insurance Benefit
Compare a listing and private-purchase proposal using the same mitigation, condition and insurance information. Adobe Group's Sedona seller article recommends preparing repair, permit and HOA records early; NAR's preparation, pricing and contingency guides support separating condition evidence from contract terms. Apply those frameworks to actual offers. Documented work can inform review without proving a fixed resale premium, guaranteed discount or universally faster closing.
Preparation choice: Obtain scoped estimates for needed work, verification and optional designation costs. Separate routine maintenance from a major reroofing or deck project. Compare the cost and time with the seller's priorities, not an assumed dollar-for-dollar price increase. A licensed insurance professional can explain carrier requirements, while the fire authority and program assess their own rules; no single party's checklist decides all three.
NAR's pricing guidance supports current property and comparable-sale analysis rather than a broad Sedona average or an insurance-related marketing label. Its contingency guide explains why price alone does not define the strength of an offer. Compare deposit, inspections, financing, insurance review, closing timing, credits and requested work. Have counsel confirm how the actual agreement treats unresolved coverage or condition questions.
Net outcome: Include commissions or stated fees, closing costs, preparation spending and carrying costs where relevant. A private route may fit a seller who wants a different schedule or avoids public marketing, but it does not erase disclosure, safety or ongoing maintenance duties. Keep known issues visible and compare the written terms rather than assuming a cash buyer cannot raise an insurance or inspection concern.
Frequently Asked Questions
Sedona sellers should separate community recognition, local assessment, completed mitigation, an active home designation and insurer decisions. Dated records explain what was done and what remains unresolved without promising fire survival or coverage. These answers use current program and local guidance while leaving parcel-specific requirements, technical work, designation status and policy terms to the relevant authority, qualified professionals, program and insurer.
Does Firewise recognition mean the house is fireproof?
NFPA describes Firewise USA as a voluntary community recognition framework. Buyers still need to review the individual structure, maintenance and actual mitigation records.
Can Sedona Fire District provide a home assessment?
The district's outreach page says Community Risk Reduction offers Firewise inspections for a home or community. Retain the dated recommendations and distinguish the assessment from proof that all work has been completed.
Is Wildfire Prepared Home available in Arizona?
IBHS announced Arizona availability in April 2026. The actual property must still meet eligibility and every requirement for its selected level.
Are cactus and succulents exempt in the IBHS immediate zone?
The current FAQ says even cactus, succulents and irrigated vegetation are not exceptions in its zero-to-five-foot noncombustible zone. Legal restrictions and property-boundary issues must be resolved rather than bypassed for the designation.
Does an application payment prove the home is designated?
An application starts a review and is not an issued certificate. Keep the evaluation, corrections and actual designation approval separately.
How long does the current home designation last?
IBHS says the designation is valid for three years with annual photo-based reviews after year one and in year two. Current conditions and maintenance must continue meeting the program requirements.
Can the designation transfer to a new homeowner?
The current FAQ permits a property-certificate transfer through the program for a fee after closing. That does not automatically transfer the seller's insurance or replace the buyer's coverage review.
Is an insurance discount guaranteed after mitigation?
IBHS says discounts are not guaranteed and vary by insurer and state. Ask the actual insurer which evidence it will review and what terms it will offer for the address.
Does a direct sale remove insurance and disclosure questions?
A private purchase does not itself erase safety, maintenance or disclosure duties. Compare the actual written proposal and remaining reviews using the same records as a listed sale.
How Maison Off-Market Reviews a Sedona Sale Option
Maison Off-Market describes a direct-purchase process that reviews the property before proposing price and timing. A Sedona seller can compare that written option after organizing mitigation, condition and insurance information. The company does not issue a wildfire designation, certify fire safety or guarantee coverage. Ask how the actual proposal addresses further investigation, known issues, remaining work and the closing conditions.
The company's stated process describes flexible closing dates, no commissions and no seller closing costs, working with the owner's attorney or title company. Confirm the actual purchaser, deposit, net proceeds and written conditions. These statements do not guarantee an insurance discount, a mitigation premium, IBHS approval or that every inspection is unnecessary.
Decision evidence: The written proposal and transaction terms, not a verified Sedona wildfire-mitigation savings case study. Compare a private route with listing and any scoped preparation using the same known facts. A direct purchase is a sale option, not permission to describe a property as fireproof or omit an unresolved condition, nonrenewal or coverage issue from the appropriate transaction review.
Compare your options before committing. Request a written private offer for your property, with no obligation, then weigh it against your listing plan.
Sources
- Sedona Fire District, Checked October 6, 2026. Public Education and Firewise Outreach. https://www.sedonafire.org/public-education-outreach/.
- Sedona Fire District, Checked October 6, 2026. Development, Current Fire Code and WUI Review. https://www.sedonafire.org/development-construction/.
- Sedona Fire District, Checked October 6, 2026. Resolution Adopting the Updated Fire Code. https://www.sedonafire.org/wp-content/uploads/2026/04/SIGNED-FINAL-RESOLUTION-2024-IFC-4-21-26.pdf.
- IBHS, Checked October 6, 2026. Arizona Expansion of Wildfire Prepared. https://ibhs.org/ibhs-news-releases/ibhs-expands-wildfire-prepared-program-to-10-addtional-states/.
- IBHS, Checked October 6, 2026. Updated Home, Neighborhood and Multifamily Requirements. https://ibhs.org/ibhs-news-releases/ibhs-rounds-out-wildfire-prepared-program-with-neighborhood-and-multifamily-standards-updates-home-requirements/.
- IBHS, Checked October 6, 2026. Wildfire Prepared Home Frequently Asked Questions. https://wildfireprepared.org/frequently-asked-questions/.
- IBHS, Checked October 6, 2026. Current Home Technical Standard. https://wildfireprepared.org/home-technical-standard/.
- NFPA, Checked October 6, 2026. Firewise USA Community Wildfire Risk Assessment. https://portal.firewise.org/sites/default/files/2020-09/Firewise%20USA%20Community%20Risk%20Assessment%202020.pdf.
- Dennis Riccio / CAAR, Checked October 6, 2026. Beyond Firewise: Why Homes Need Fire Hardening Too. https://caaraz.com/beyond-firewise-why-rim-country-homes-need-fire-hardening-too/.
- Esther Talbert / Yavapai Realty, Checked October 6, 2026. Keep Your Sedona Property Insured: IBHS and Mitigation Records. https://www.yavapairealty.com/blog/ibhs-wildfire-solution.
- Sedona Real Estate Agents, Checked October 6, 2026. Firewise Living in Sedona. https://sedonarealestateagents.com/firewise-living-in-sedona-how-homeowners-can-protect-their-property-from-wildfire-risk/.
- Adobe Group, Checked October 6, 2026. Selling a Home in Sedona: Preparation and Review. https://adobegr.com/blog/selling-a-home-in-sedona-step-by-step-game-plan.
- Arizona DIFI, Checked October 6, 2026. Home Insurance Consumer Information. https://difi.az.gov/consumers/homeowners-insurance.
- Arizona DIFI, Checked October 6, 2026. Homeowners Insurance Frequently Asked Questions. https://difi.az.gov/homeowners-insurance-frequently-asked-questions.
- NAR, Checked October 6, 2026. Preparing to Sell Your Home. https://www.nar.realtor/the-facts/consumer-guide-preparing-to-sell-your-home.
- NAR, Checked October 6, 2026. Real Estate Contract Contingencies. https://www.nar.realtor/the-facts/consumer-guide-real-estate-contract-contingencies.
- National Association of REALTORS, Checked October 6, 2026. Consumer Guide: What Goes Into Pricing Your Home. https://www.nar.realtor/the-facts/consumer-guide-what-goes-into-pricing-your-home.
Related research

Seller Guide · October 6, 2026
How to Prepare Point Pleasant Beach Rental Records Before Selling
Separate rental approval, income history and booked stays before comparing sale terms.

Seller Guide · October 6, 2026
How to Prepare Rumson Flood and Waterfront Records Before Selling
Separate flood disclosure, elevation, repairs and waterfront rights before comparing sale terms.

Seller Guide · October 6, 2026
How to Prepare Sarasota Condo Inspection and Reserve Records Before Selling
Separate building condition, reserve funding and resale documents before comparing sale terms.